Personal Injury Case? How Ray Fought a Denied Claim Without a Lawyer
Two surgeries, more than $80,000 in medical bills and an insurer that denied the claim. Ray defeated summary judgment, prepared for trial and settled for $250,000.
A composite story drawn from member experiences. Details below.
Ray ran a mobile auto-detailing business. He loaded supplies before breakfast, drove to customers’ homes and fit appointments around school pickups for his niece. He wanted to be the uncle she could count on, and the person his customers called.
On one job, his equipment ignited fumes near a damaged vehicle. He was badly burned. He believed the homeowner knew about a fuel leak and hadn’t warned him. The homeowner disputed that and blamed Ray’s equipment. The insurer denied the claim.
His first instinct was to send the insurer his injury photographs and demand payment. Two surgeries and more than $80,000 in bills felt like proof enough. But the photographs showed what happened to his body, not who was legally responsible for it.
The homeowner had defense counsel. Ray talked with contingency-fee lawyers, but he felt they undervalued his claim and worried they’d settle low. That was his read of the options he was offered, not a rule about lawyers. He chose to prepare his own case.
See if your case qualifies →5 questions. 2 minutes. $1 once. Nothing renews.
Proof: a serious injury wasn’t the whole case
In Proof, Ray separated four questions: what the homeowner knew, whether Ray could have discovered the danger himself, what caused the fire, and what he lost. He saved the job messages, photographs, equipment information, treatment records and bills, and marked where he still needed evidence.
What Ray had to prove
Being hurt at a customer’s home doesn’t make the customer responsible. Here’s what he matched to each question.
| Question | His evidence |
|---|---|
| What duty did the homeowner owe him? | The job arrangement and the rules for people who hire independent contractors |
| What hazard existed, and who knew? | Vehicle repair records, messages and testimony about the leak before the job Gap found He’d listed a text about the leak as a warning before the job. The timestamp showed it was sent after the fire. |
| Could Ray have found it himself? | What he knew before starting, his inspection and the scope of the job |
| What caused the injury? | Incident evidence plus qualified technical and medical opinions, not photographs alone |
| What did he lose? | Treatment and payment records, business accounts and the work he couldn’t do |
Injury law, contractor rules and deadlines vary by state. Proof shows the elements that apply in your court.
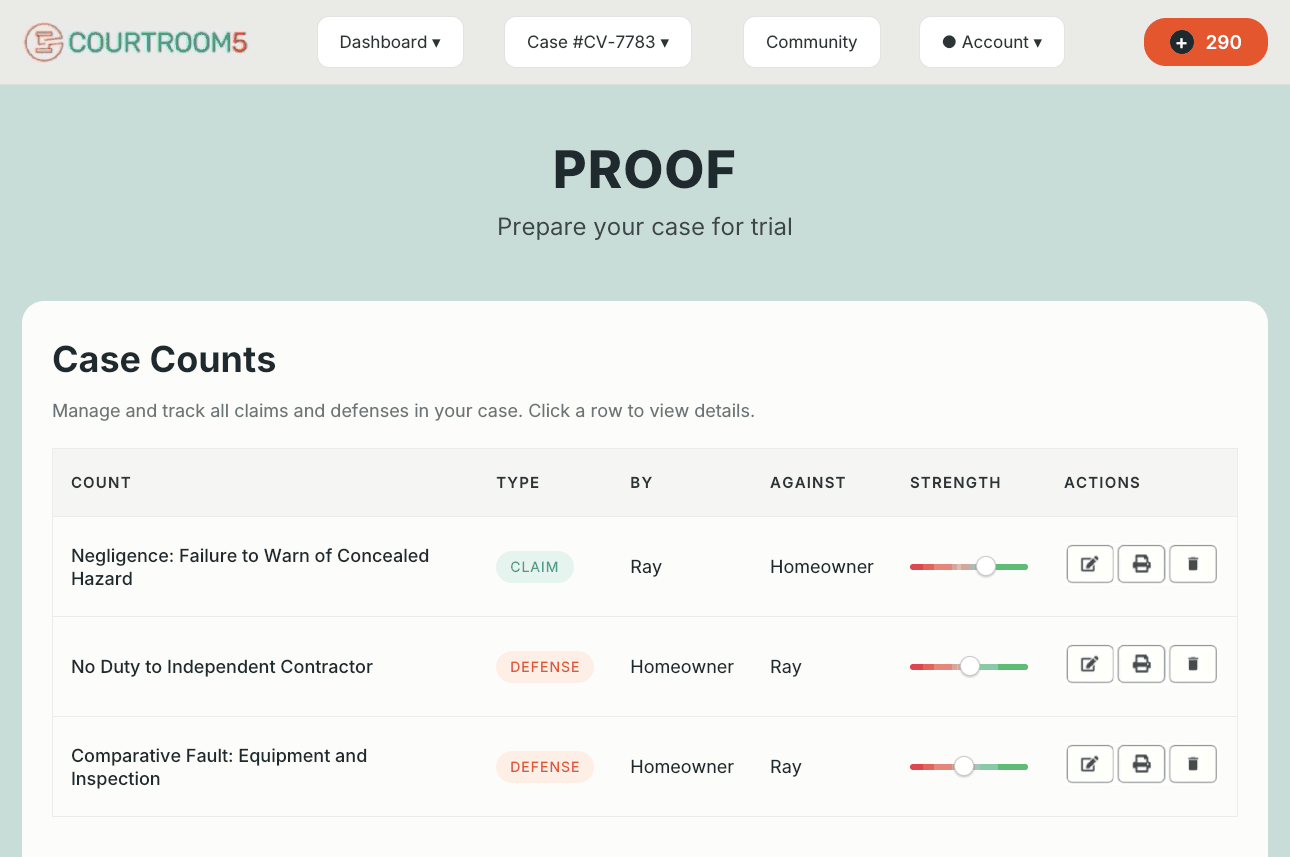
He corrected the text’s place in his timeline before filing. That message couldn’t show the homeowner knew in advance, so he’d need other evidence that could.
Doubt, at the work van
One morning, Ray opened the van and tried to lift a supply container. He set it back down. He wasn’t ready for a normal day of appointments, and the fear wasn’t only about court. What if the business couldn’t support him anymore?
He closed the van and kept his treatment appointment. Later, a Learning Center lesson helped him separate a question about fault from a question about damages. His next task was one corrected entry, not the whole case.
Strategy: check the duty before choosing the claim
Strategy helped Ray research the rule that decided his case. In California, someone who hires an independent contractor generally leaves job safety to the contractor. One exception: a hirer who knows about a hidden hazard and doesn’t warn the contractor. Ray’s own knowledge, and whether he could have found the leak, mattered too.
He also checked his filing deadline. Talking with an insurer didn’t stop the clock.
Finding experts who could answer the hard questions
Ray searched professional directories and asked for referrals. He compared qualifications, conflicts, availability and written fees, then hired experts himself to give their own opinions, not promised ones.
- A fire investigator examined the ignition, the alleged leak and whether Ray could reasonably have detected it.
- A burn specialist addressed his injuries, and a life-care planner estimated future treatment and costs from his medical records.
- Vocational and economic experts assessed his ability to work and his future income losses.
Courtroom5 helped him identify the questions and organize the record. The experts supplied the answers within their expertise.
Hurt on someone else’s property, or on the job, and the insurer said no?
See if your case qualifies →$1 gets you 100 credits and community access. Nothing renews.
Damages beyond the first bills
Ray’s recovery plan included treatment, rehabilitation, help with daily tasks and a gradual return to work. Appointments and rest stayed on the calendar next to case tasks.
His damages included future care and lost income, not just bills already due. He caught a second mistake here: canceled bookings were lost revenue, not lost profit. He subtracted the expenses he hadn’t had to pay and made sure the same future loss wasn’t counted twice. His $600,000 demand covered his supported past and future losses and his pain. It was his demand, not a court’s valuation.
The complaint, then hard questions
In Documents, Ray prepared a negligence complaint built on what his records supported, checked the facts and court requirements, filed it and arranged service.
Discovery cut both ways. He requested the vehicle records and messages, and answered the defense’s questions about his equipment, his inspection and his losses. A repair record from before the job, plus testimony, supported his claim that the homeowner knew about the fuel problem. He went back to Proof. His case no longer depended on the mistimed text.
The summary judgment hearing
The homeowner moved for summary judgment, arguing the case could be decided without a trial. Ray prepared an opposition with evidence the court could consider, including the required separate statement. Judge Practice made him rehearse the questions he had to answer.
At the hearing, Ray tied each disputed point to evidence: the pre-job repair record and testimony, the investigator’s analysis, and the medical evidence linking the fire to his injuries. He didn’t ask the judge to treat his bills as an answer to the duty question.
The judge found real factual disputes for a jury to decide and denied the motion. That wasn’t a finding that the homeowner was liable. It meant the homeowner couldn’t win without a trial. Ray started preparing witnesses, expert testimony and exhibits.
A hard bargain, backed by a trial-ready case
Ray kept his $600,000 demand on the table and explained it with his loss calculations and life-care plan, knowing a jury might award less or rule against him. The failed motion changed the negotiation. He could credibly say he’d put the evidence before a jury rather than take a token payment.
The parties settled for $250,000. It was well below his demand, and a substantial recovery on a claim the insurer had denied. Ray was happy with it. He chose certainty over the risk and cost of trial, and he considered it a win.
He got independent advice on the release, then checked medical liens, insurance reimbursement and case costs. The $250,000 was the gross amount, not what he could spend. He confirmed the payment, filed the dismissal and checked the court record until the case was closed. There was no admission of liability.
What a case like this costs
On Courtroom5, you see the price of every step before you take it. Typical ranges:
- Analyzing your case and the legal issues: about 165–270 credits
- Drafting one document (such as a complaint or an opposition to summary judgment): about 225–725 credits
- Preparing for and responding to discovery: about 420–1,385 credits
Your first 100 credits are $1. After that, credits are 15¢ each, or 1,000 a month with Max for $99. Community, office hours and courses never use credits.
Plan for outside costs too. In an injury case like Ray’s, experts are the biggest expense: investigators, doctors and life-care planners each charge their own fees. Add filing, service and deposition costs. Courtroom5 doesn’t cover these.
Back to work, in smaller steps
The settlement helped cover treatment and a gradual return to work. It didn’t erase the lost months or guarantee a full recovery. Ray kept his appointments, reviewed his equipment and safety checks, and took work within his limits. His family still helped on the hard days.
He put the closing papers away and checked the route for one manageable booking. There would be time to pick up his niece afterward.
Litigate like your case matters.
Hurt while working on someone else’s property?
Save the incident records and photos, and check your filing deadline now. Talking to an insurer doesn’t stop it. If you’re ready to prepare your case, see whether the LAW Accelerator fits.
See if your case qualifies →5 questions. 2 minutes. $1 once. Nothing renews.
About this case study. Ray is a composite drawn from the experiences of Courtroom5 members, not a report of one person’s case. Dollar amounts are illustrative. This story uses a California case involving an independent contractor; injury law, contractor duties, deadlines and procedures vary by state. Outcomes vary. Courtroom5 is not a law firm and does not provide legal advice. This case study is not a promise of results.
See if we can help. Start for $1